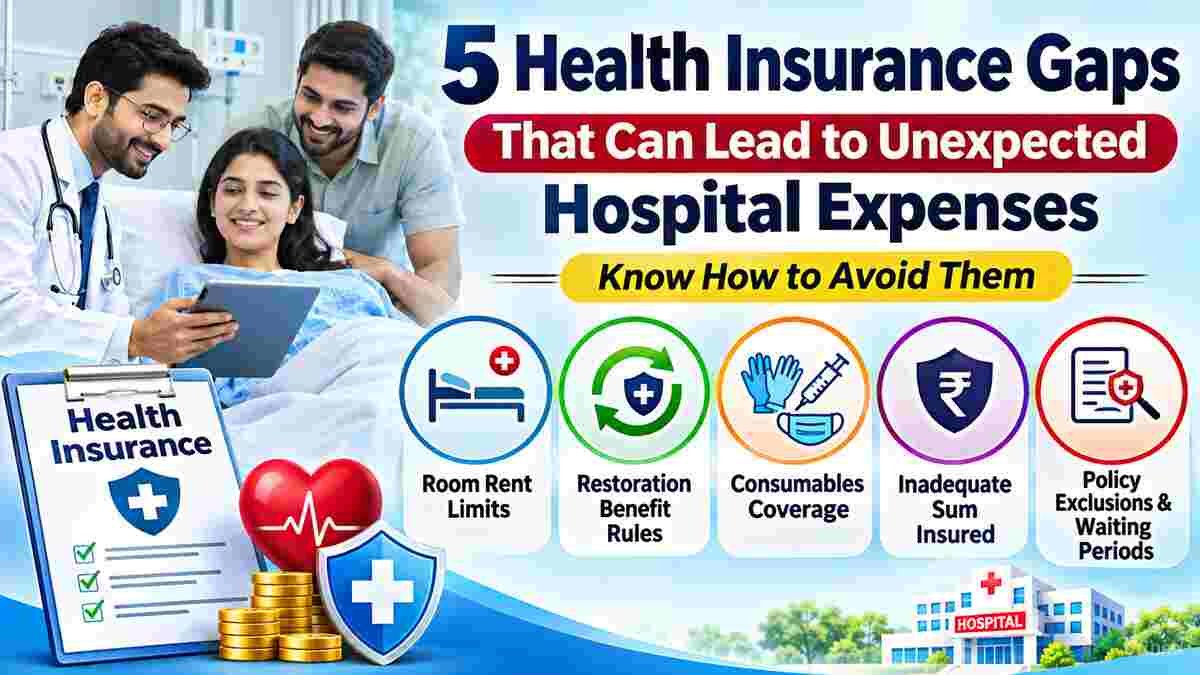
Health Insurance Tips: Having a health insurance policy with a ₹10 lakh sum insured does not necessarily mean every hospital expense will be covered. Room rent restrictions, consumables exclusions, restoration benefit conditions and inadequate coverage can leave policyholders paying additional money from their own pockets. Here are five important health insurance gaps you should understand before purchasing a policy.
Health insurance is an essential financial safety net against rising medical expenses. However, many policyholders discover the limitations of their insurance coverage only when they receive a hospital bill or file a claim.
For example, imagine purchasing a health insurance policy with a sum insured of ₹10 lakh. You may expect the insurer to pay the entire hospital bill if you require treatment. However, certain expenses may be excluded, restricted or covered only under specific conditions.
As a result, you could still face significant out-of-pocket expenses despite having an active health insurance policy.
This does not mean health insurance is ineffective. Instead, it highlights the importance of understanding policy exclusions, sub-limits, waiting periods and additional benefits before choosing coverage.
Here are five common health insurance gaps that could catch you off guard and practical ways to avoid them.
1. Ignoring Room Rent Limits in Health Insurance Policies
One of the most overlooked features of a health insurance policy is the room rent limit.
Some insurance policies restrict the amount a policyholder can claim for hospital room accommodation. This restriction may be expressed as a fixed daily amount or a percentage of the total sum insured.
For example, if your health insurance policy provides coverage of ₹10 lakh and has a room rent limit of 1% of the sum insured, your eligible room rent may be restricted to ₹10,000 per day.
If you choose a hospital room costing more than the permitted limit, you may have to pay the additional amount yourself.
Depending on the policy wording, choosing a room above the permitted category could also result in proportionate deductions on certain associated medical expenses. This can increase your financial burden considerably.
Although several modern health insurance policies offer no room rent restrictions, policyholders should never assume that every plan provides this benefit.
How to avoid this problem:
-
Check whether the policy has a room rent limit.
-
Look for plans offering no room rent restrictions.
-
Understand whether ICU charges have separate limits.
-
Check whether choosing a higher-category room affects other claim expenses.
-
Compare the policy wording before making a purchase.
2. Not Understanding Health Insurance Restoration Benefits
A restoration benefit is another important feature that can help policyholders manage multiple hospitalisation expenses during a policy year.
Under this feature, the insurer restores the sum insured when the original coverage is exhausted or reduced, subject to the policy’s terms and conditions.
For example, suppose you have a health insurance policy with a ₹10 lakh sum insured. If a major hospitalisation exhausts the available coverage, the restoration benefit may replenish the insurance amount for a subsequent eligible claim.
However, restoration benefits do not work identically across all insurance policies.
Some insurers activate restoration only after the entire sum insured has been exhausted. Others may offer partial restoration when a portion of the coverage has been utilised.
There may also be restrictions concerning:
-
Whether restoration applies to the same illness or a different illness.
-
Whether the benefit is available for the same insured person.
-
Whether multiple claims are permitted during the policy year.
-
Whether restoration can be used for the first claim.
-
Whether there are specific conditions for activating the benefit.
How to avoid this problem:
Before purchasing a policy, carefully examine the restoration benefit conditions. Understand when the coverage is restored, whether it can be used for multiple claims and whether the restored amount applies to the same or different illnesses.
Do not choose a policy simply because it advertises unlimited restoration. Read the actual policy wording to understand its limitations.
3. Overlooking Consumables Coverage in Health Insurance
Hospitalisation involves more than doctors’ fees, medicines, diagnostic tests and room charges.
Hospitals also use several disposable medical items during treatment, including:
-
Surgical gloves
-
Syringes
-
Masks
-
Personal protective equipment (PPE) kits
-
Disposable medical supplies
-
Other single-use hospital materials
These expenses are commonly classified as consumables.
Depending on the insurance policy, certain consumable expenses may be excluded from the standard coverage. Consequently, patients may have to pay these charges separately even when the main hospitalisation claim is approved.
Many insurance companies offer consumables coverage through additional benefits or add-on covers.
However, the items covered under these benefits can differ considerably between insurers. Two policies offering an add-on with a similar name may not necessarily provide identical protection.
How to avoid this problem:
-
Check whether consumables are included in the base policy.
-
Review the list of covered and excluded consumable items.
-
Compare the conditions of consumables-related add-ons.
-
Understand whether the benefit has a separate limit.
-
Check whether the add-on applies to all eligible hospitalisation claims.
A detailed understanding of consumables coverage can help prevent unexpected deductions when settling hospital bills.
4. Depending Entirely on Employer-Provided Health Insurance
Many salaried employees depend entirely on the group health insurance policy provided by their employer.
While employer-sponsored health insurance can provide valuable medical protection, relying exclusively on it may create problems in the long run.
The biggest concern is that employer-provided insurance is generally linked to employment.
If you resign, switch jobs, lose your employment or retire, your existing group health insurance coverage may end, depending on the policy arrangements.
This can leave you without adequate medical insurance protection at a time when obtaining a new individual policy may be more difficult or expensive.
Medical expenses can also increase with age, making long-term insurance planning particularly important.
Another concern is that the coverage amount under an employer’s group policy may not be sufficient for your family’s medical requirements.
How to avoid this problem:
Consider purchasing an individual or family floater health insurance policy in addition to employer-provided coverage.
Before selecting a personal policy:
-
Evaluate your family’s medical requirements.
-
Choose an appropriate sum insured.
-
Compare individual and family floater plans.
-
Understand waiting periods and pre-existing disease conditions.
-
Review portability and migration options under applicable regulations.
Having independent health insurance can provide greater continuity and flexibility, regardless of changes in your employment.
5. Choosing Unnecessary Add-Ons Instead of Adequate Base Coverage
Insurance companies offer several additional benefits, including critical illness covers, daily hospital cash, consumables coverage and other optional features.
Although these add-ons can provide useful protection, purchasing multiple benefits without evaluating your actual requirements may increase your premium unnecessarily.
For instance, daily hospital cash provides a predetermined amount for each eligible day of hospitalisation, subject to policy conditions. However, it is not designed to replace comprehensive hospitalisation coverage.
Similarly, disease-specific benefits may offer additional financial protection but may not address broader medical expenses.
One common mistake is spending more on optional features while keeping the basic health insurance sum insured too low.
How to avoid this problem:
Prioritise an adequate base health insurance policy before purchasing optional benefits.
Consider the following approach:
-
Select a suitable base sum insured according to your family size, location and medical requirements.
-
Evaluate useful add-ons such as consumables coverage.
-
Compare premiums against the actual benefits offered.
-
Avoid paying for features that do not match your requirements.
-
Consider a super top-up policy to increase overall financial protection.
A super top-up plan can provide additional coverage after eligible expenses cross a specified deductible during the policy year. However, its deductible and claim conditions should be examined carefully.
What Should You Check Before Buying a Health Insurance Policy?
Choosing health insurance requires more than comparing premiums and the advertised sum insured.
A policy with a lower premium may contain restrictions that increase your out-of-pocket expenses during hospitalisation. Similarly, a more expensive policy is not automatically the best option.
Before purchasing health insurance, carefully evaluate these important factors:
| Policy Feature | What You Should Check |
|---|---|
| Sum Insured | Whether coverage is adequate for your family |
| Room Rent | Daily room rent and ICU restrictions |
| Restoration Benefit | Activation conditions and claim eligibility |
| Consumables | Covered items and exclusions |
| Waiting Period | Initial, specific illness and pre-existing disease waiting periods |
| Co-payment | Percentage of eligible expenses payable by you |
| Sub-limits | Treatment-specific financial restrictions |
| Exclusions | Expenses and treatments not covered |
| Add-ons | Actual benefits, limitations and additional premiums |
| Claim Process | Cashless network and reimbursement procedures |
You should also review the insurer’s claim settlement process, hospital network and grievance redressal arrangements.
Most importantly, read the policy wording and customer information sheet rather than relying only on promotional material.
Final Takeaway: Choose Health Insurance That Protects Your Savings
Health insurance can provide valuable financial protection against unexpected medical expenses, but the effectiveness of a policy depends on its actual coverage and conditions.
Room rent restrictions, restoration benefit rules, consumables exclusions, dependence on employer-sponsored coverage and unnecessary add-ons are five areas that deserve special attention.
Before purchasing a policy, make sure you understand what is covered, what is excluded and how much you may have to pay during a claim.
An effective health insurance policy is not necessarily the one offering the maximum number of features. It is the one that provides suitable medical coverage, transparent conditions and financial protection when you need it most.
If you are unsure about the policy terms, consult a qualified insurance advisor and compare multiple plans before making your final decision.





Discussion about this post